


Secular Stagnation in Occlusion, Yet Global Savings Glut Still in the Foreground: With Fed policy frozen for at least the summer, the monetary muddle continues: Today’s discount rates reveal the real anxieties haunting global finance, while the Fed’s dot plots reveal a split committee, and hence one that has to be modeled not as a rational but as a confused actor…
Remember when the future was really cheap? The market’s discounting of long-term value has quietly shifted, exposing deep uncertainties about growth, savings, and the persistence of chaos-monkey governance. The market’s real interest rate calculus has changed. The “normal” macroeconomic world of the 1990s is a fading memory, replaced by a regime where the future is more valuable, but hardly secure—still haunted by the global savings glut, if not full-blown secular stagnation, with policy uncertainty never far from the stage.
Across my screen comes the very sharp Tim Duy, who writes:
Tim Duy: Fed Watch, 6/18/25 <https://public.hey.com/p/5gobQ2gmfq4owmTHRvNSgCcY>: ‘The path to a [Federal Reserve] rate cut begins with inflation coming in below expectations [of 0.3%-points per month] over the summer, which means that tariffs are absorbed in the economy somewhere other than in consumer prices, or that service sector disinflation compensates for tariffs. There is a lot of data between now and September. The Fed’s not going to know what it’s doing until it gets its hands on that data.…
The SEP projections for 2026 and 2027 show slightly more persistent inflation than previously expected. This is, perhaps, a nod to the structural forces—demographics, deglobalization, fiscal expansion—that have made the post-plague world so challenging for central bankers.
And Tim Duy notes that the Federal Reserve is now substantially and evenly split. Barkin, Hammack, Kugler, Logan, Musalem, Schmid, and Williams are expecting and hoping to hold interest rates constant throughout the rest of 2025. Bostic and Kashkari are pencilling in one 25%-point rate cut. Barr, Collins, Cook, Daly, Goolsbee, Harker, Jefferson, and Powell are pencilling in two cuts. And Bowman and Waller believe an 0.75%-point rate cut before January would be appropriate.
For the no-big-shock longer run, the hawks see the neutral Fed Funds rate that is the economy’s aggregate demand-supply balance point as still at something like 3.75%/year; the doves see it as 2.75%. (With the current 3-Month Treasury-Bill rate at 4.2%/year and the 10-Year Bond rate at 4.4%/year; and trailing-year CPI core inflation at 2.75%/year.)
With a confused and evenly split FOMC, the Fed’s stance is firmly “wait and see.” Summer inflation news, primarily driven by the evolving impact of Trump chaos-monkey tariff governance, ought to be decisive. Then again, history teaches us that “the next six months will probably be decisive” is more often than not an unhelpful cl=op-out.
Meanwhile, the Fed is comfortable holding steady as long as the buffering labor market remains solid and growth continues, with weakness spreading but still below any recessionary trigger level. The June FOMC meeting left policy rates unchanged, as had been widely expected, given how the committee adrift between conflicting economic signals and riven by internal division. Nine participants expect one or no cuts in 2025; ten expect two or three. And those diverging paths diverge further as people try to peer through the veil of time and ignorance to assess the longer run.
Powell appears to want to downplay the significance of dot-plot division, calling it a snapshot of individual guesses rather than the result of a committee deliberation that had led to the coalescence of diverging camps. Powell emphasized that all remains in the air: “everyone would agree that they’re all going to be data dependent”. Powell emphasized that no one on the committee is wedded to their projections. “No one holds these rate paths with a great deal of conviction,” he said.
This approach is, I think, both prudent and perilous. Prudent, because the world is genuinely uncertain: the impact of tariffs is unclear, inflation has been softer but remains sticky, and the labor market—while still strong—shows some signs of cooling. Perilous, because the Fed’s explicit data dependence invites markets to overreact to each new data point, amplifying volatility and making policy communication even more challenging.
Powell hinted that the key uncertainty—of course—is the impact of tariffs. Are there any buffers to keep them from feeding through into consumer prices? Might we expect some offset from disinflation in services? As Duy says, if there is a path to a rate cut, it “begins with inflation coming in below expectations over the summer”. That requires that tariffs by absorbed somewhere, resulting in core-PCE inflation printing (when did people start using that word that way?) at 0.2s or lower starting now.
The Fed is waiting to see.
And so the Fed is, now, on autopilot—content to wait, watch, and gather information, with both doves and hawks poised to change their stance should the data shift.
Stepping back:
Starting back in the Clinton administration, the then-Alan Greenspan Fed settled on what came to be regarded as a “normal” configuration of the macroeconomy: a core inflation rate of 2.5%/year on a CPI-basis (and 2.0%/year on a PCE-basis); a short-term safe real interest rate of 2.5%/year; and a term-structure duration-risk slope of 1.25%-points/year going from the 3-month to the 10-year Treasury:
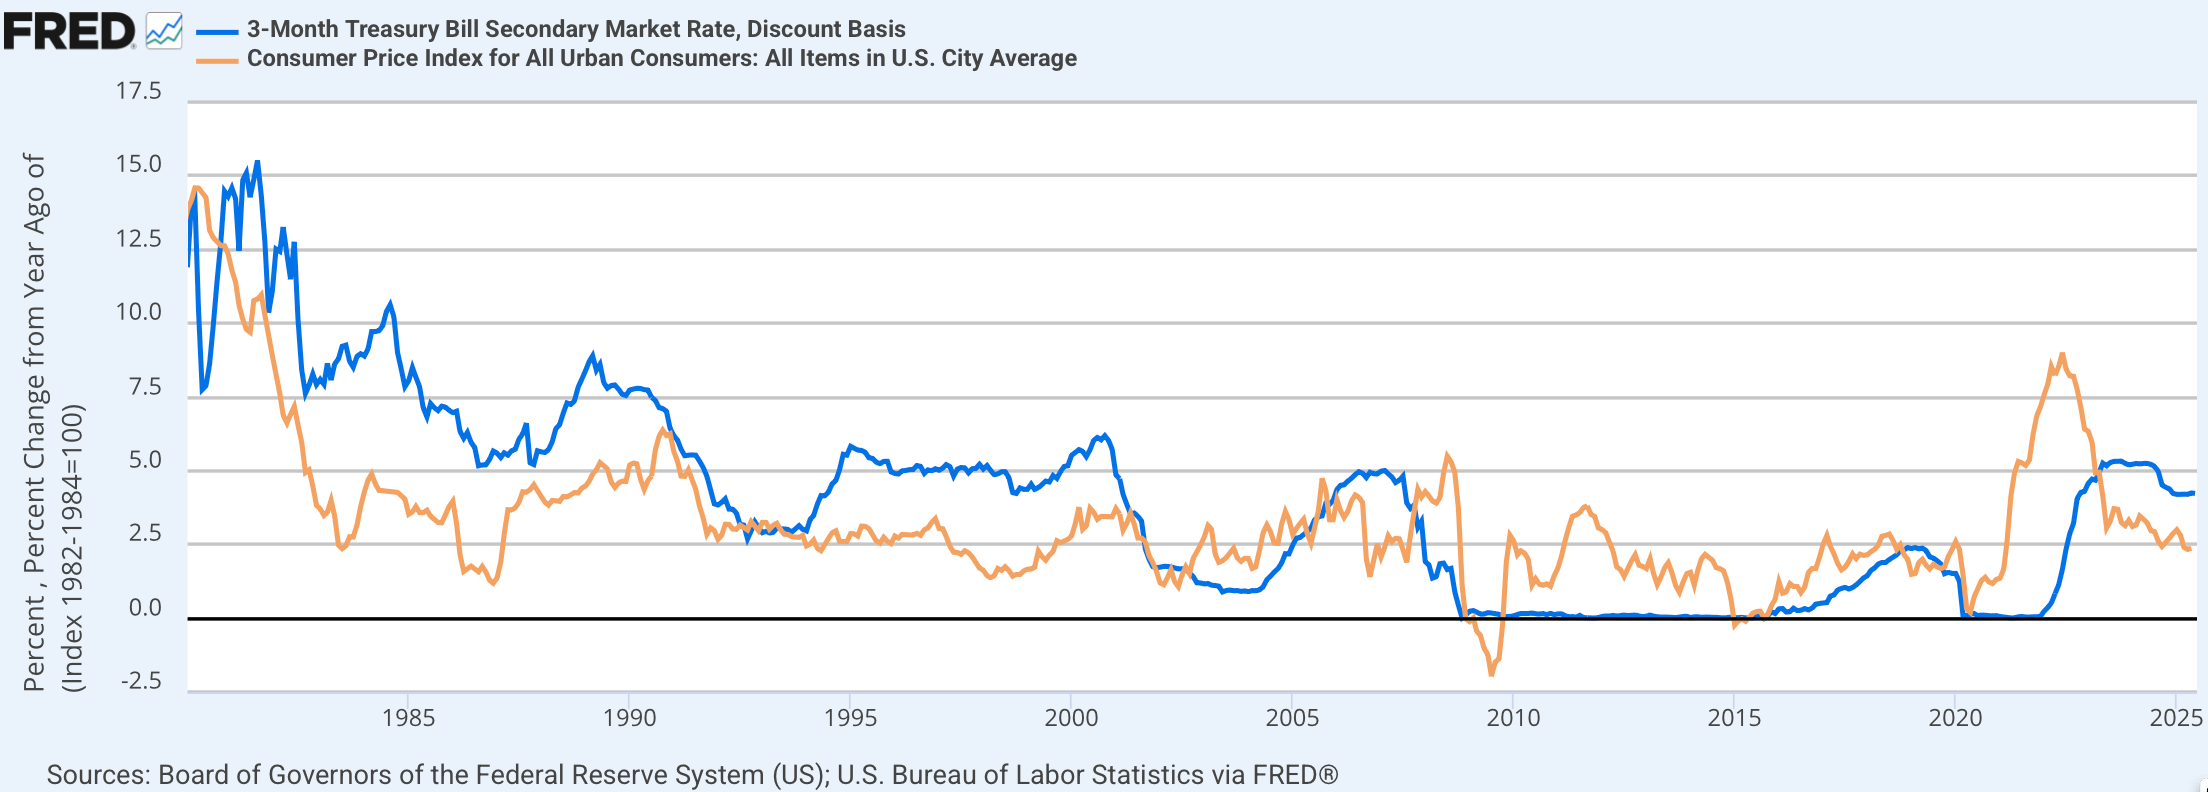
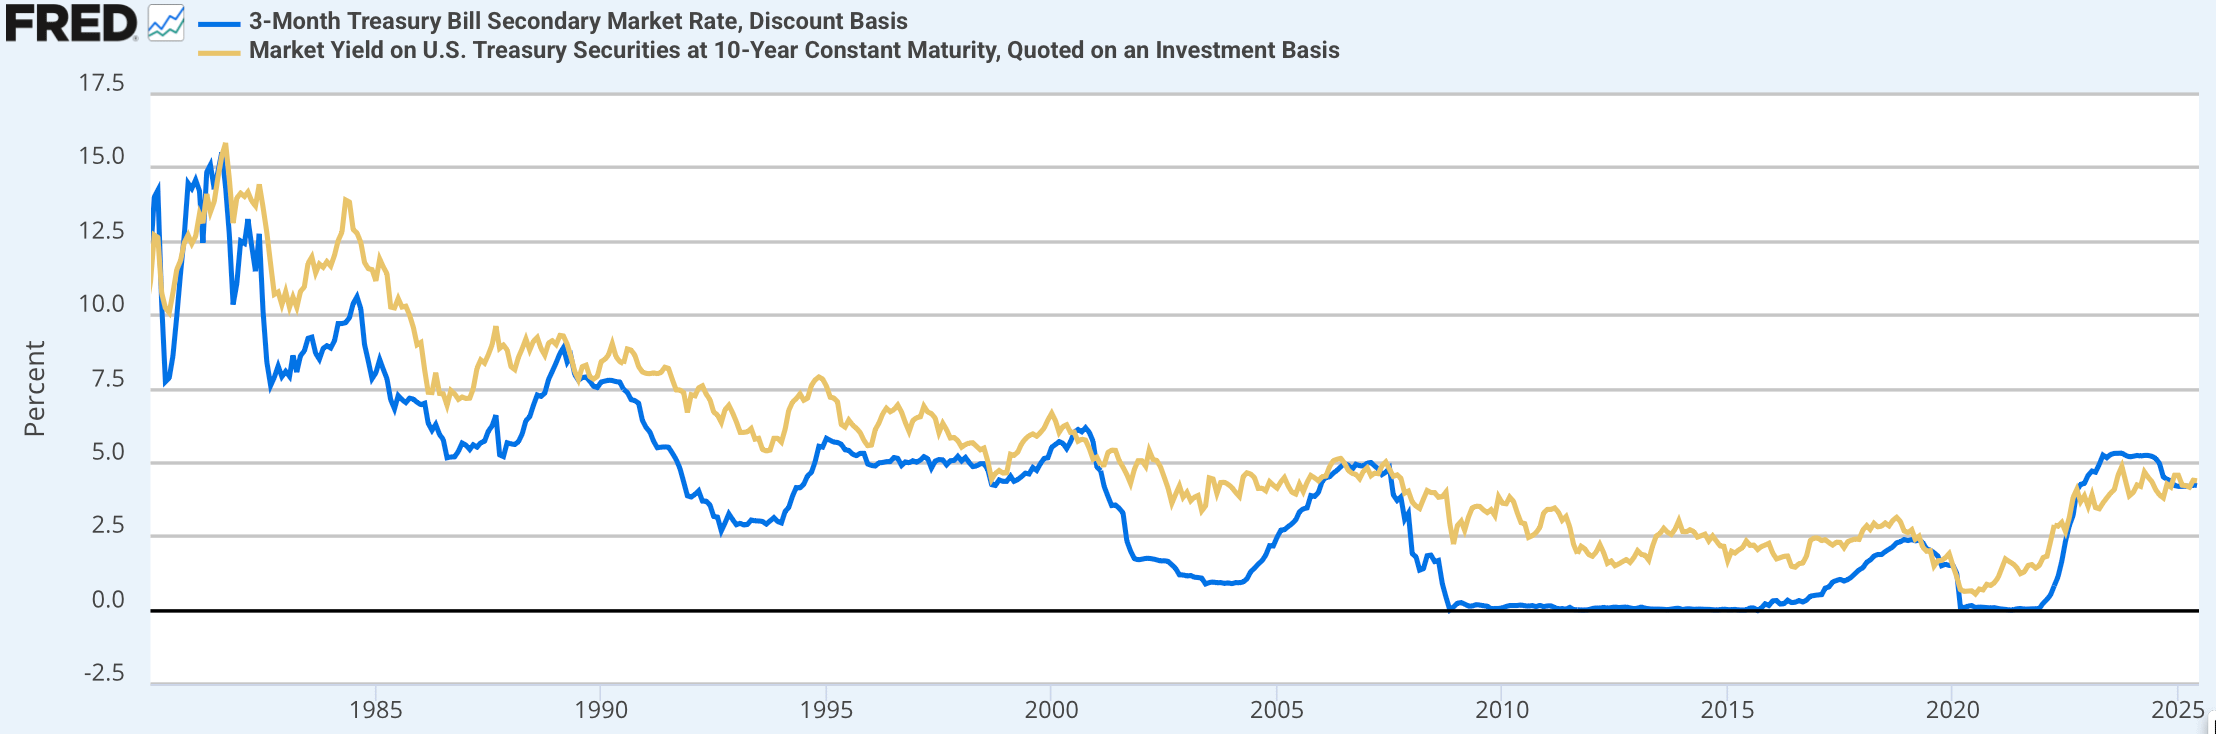
That has continued to guide expectation of a “normal” economy for more than a generation now. But the economy has never been normal.
Compare right now with the end of 1997, when we had a Treasury-Bill interest rate of 5.25%/year and a 10-Year Treasury-Bond interest rate of 5.75%/year, with a trailing annual core CPI inflation rate of 2.25%/year. Right now our trailing inflation rate is 50%-points/year higher; our 10-Year rate is 1.35%-points/year lower, and our Treasury-Bill interest rate is 1.00%-points/year lower. That gives us a long real interest rate 1.5%-points/year lower than back in the later 1990s, and a term-premium slope that I interpret as (most likely) a market that is aligned with the doves and that expects a further four 25%-point rate cuts over the next year and a half should the economy return to normal.
OK. By now your eyes have all glazed over. This is what all this means:
Relative to the ideas of a “normal” macro-financial economy as they settled back in the 1990s Clinton-Greenspan “Great Moderation” era:
The market sees a “normal” long-term safe real interest rate in a balanced economy of not 3.75%/year but of 2.5%/year.
The market sees either (a) chaos-monkey governance ending, and short-term Treasury rates falling by an additional 1.5%-points as the economy normalizes; or (b) a recession, and a serious need for rate cuts to try to cushion the damage.
Half the Fed sees that—that is, either (a) or (b) above.
The other half of the Fed sees either growth stronger, saving weaker, or the burden of the debt starting to bite to such a degree that “secular stagnation” or the “global savings glut” is no longer a thing.
In that context, we can say:
The period from 2010 to 2022 was defined by what Larry Summers dubbed “secular stagnation”—a regime in which the equilibrium real interest rate, r*, hovered perilously close to zero. The implication was stark: the market, in its collective wisdom (or perhaps folly), valued a dollar of real purchasing power two decades hence nearly the same as a dollar of real purchasing power today. Capital was so abundant, and investment opportunities so scarce, that the time value of money effectively vanished at the margin.
This was not some theoretical curiosity but a lived reality for pension funds, insurance companies, and anyone else seeking long-duration safe assets. The causes—demographic stagnation, tepid productivity growth, a global glut of savings from East Asia and Germany, and the hangover from the Global Financial Crisis—have been dissected ad nauseam, but the empirical upshot was clear: the normal rules of intertemporal choice seemed suspended.
In contrast, during the earlier “global savings glut” configuration that had emerged post-2001 and pre-2009—memorably diagnosed by Ben Bernanke—was much less extreme. However, it was still remarkable by historical standards. The world, awash in excess savings from export-driven economies, bid up the price of safe assets and drove down yields. Yet, unlike the secular stagnation era, the market still assigned a non-trivial discount to the future: a unit of purchasing power twenty years out was judged to be worth roughly two-thirds of one today.
This régime was not “normal” in the 1990s sense—when the twenty-year real cumulative discount was effectively half. But it was still a world in which the future mattered less than the present, just not as much as it once had. The persistence of this configuration, despite ballooning U.S. deficits and the Federal Reserve’s attempts to “normalize” policy, suggests that the underlying drivers—demographic shifts, global capital flows, and a nagging fear of chaos-monkey policy chaos—remain stubbornly in place today.
But this is just the market view. And the market view is often wrong.
Oh goody! The return of one of my favorite mistaken notions, “saving glut,” "Investment dearth" is more like it.
The developing world needs bazillions of investment even to “get to Denmark” but they don’t have the property rights regimes to attract the domestic and foreign savings. Ditto the need for levees and seawalls and irrigation systems and new crop varieties and forest management to adapt the level of CO2 alreddy in the atmosphere.
And even the lowest cost measures to reach CO2 net zero by 20nn (a tax on net emissions) will require huge investments.
"Starting back in the Clinton administration, the then-Alan Greenspan Fed settled on what came to be regarded as a “normal” configuration of the macroeconomy: a core inflation rate of 2.5%/year on a CPI-basis (and 2.0%/year on a PCE-basis); a short-term safe real interest rate of 2.5%/year; and a term-structure duration-risk slope of 1.25%-points/year going from the 3-month to the 10-year Treasury"
There must be some combination of size and frequency of ordinary (Brownian movement) economic shocks, price stickiness (across multiple sectors, not just wages), federal deficits, tax and regulatory policies bearing on the choice between saving and investment that make this configuration growth maximizing.
Only the first two of those are plausibly slow moving enough to justify an "A" of 2% PCE in a F_A_IT regime. With tax and regulatory structures and deficits varying, why should anyone have any expectation of a "normal" level of short and long tern interest rates that the Fed might need to engineer to hold to a 2% forward looking average while flexibly adjusting inflation to deal with extraordinary shocks and policy to maximize growth?